Franchise investment opportunities give families a way to build generational wealth through an asset rather than a salary: a proven operating model, a business with resale value, and a training ground where children learn how money and management actually work. This guide covers the franchise categories worth evaluating right now and the wealth-building strategies that separate ownership from employment. It also covers the Franchise Disclosure Document (FDD) items that protect family capital and the succession planning that keeps a business intact from one generation to the next. Roughly $124 trillion is projected to change hands in the United States over the next 25 years, and most families have no plan for their share of it.
A franchise can be a way to turn the experience and capital you’ve built over your career into something you actually own. And when your family is part of the decision, the conversation becomes bigger than replacing a paycheck. You start thinking about what kind of business you want, how involved you want to be, how it could grow, and whether it could become something your family can benefit from over time.
We work with candidates in this position every week, including many in the Atlanta, Georgia market. The best place to start is with what you want the business to do for you and your family, rather than jumping straight into brands or investment figures.
Our franchise consulting process starts there. We look at your goals, your circumstances, and the kind of ownership that makes sense for you before any brand enters the conversation.
What You Should Know Before You Start
Can a franchise really become a multigenerational family asset?
- Yes, with conditions. Most franchise agreements run 10 years or longer with renewal rights, and Item 17 of the Franchise Disclosure Document (FDD) spells out whether you can transfer the business to a family member and what the franchisor requires to approve it.
- Documented systems make the handoff easier than in an independent company. A child who inherits an operations manual, a training program, and a brand inherits far more than a lease.
- No franchise carries a guarantee of success. Review every agreement with a franchise attorney before you sign.
Which franchise categories suit a family legacy plan?
- Service categories with recurring demand hold up well across economic conditions. The International Franchise Association (IFA) projects commercial and residential services and child services as the fastest-growing franchise industries in 2026, each at 3.2% year over year.
- Preventive healthcare now ranks as the third-largest franchised industry, according to the same report, and fitness and wellness concepts benefit from a customer base that keeps spending on health.
- Business-to-business services, semi-passive models, and multi-unit territories each fit a different family. The right category depends on who will run the business and for how long.
How much capital does a family need to get started?
- The amount of capital needed can differ significantly between franchise brands. Each franchisor sets its own financial requirements, and prospective franchisees should review Item 7 of the FDD for the brand’s estimated initial investment and associated costs.
- The initial franchise fee alone commonly runs from tens of thousands to several hundred thousand dollars, according to the Federal Trade Commission (FTC), with buildout, equipment, and inventory on top.
- In our consulting practice, candidates with around $100,000 to $200,000 in available liquid capital may have access to a broader range of franchise opportunities to consider.
What usually goes wrong when families try to pass wealth down?
- A 20-year study of 3,200 families by the Williams Group found that about 70% of wealthy families lose their wealth by the second generation and 90% by the third. Mostly through poor communication and unprepared heirs rather than bad investments.
- Divorces, disputes, and unclear ownership stakes fragment family assets faster than any market downturn.
- A comprehensive estate plan, reviewed after every major life change, prevents most of it. Financial professionals, not the franchisor, handle that side of the work.
Table of Contents
- What Generational Wealth Means for a Franchise Family
- Franchise Investment Opportunities Worth a Closer Look
- Wealth Building Strategies That Separate Ownership From a Salary
- Financial Qualification: Liquid Capital, Net Worth, and Funding
- FDD Due Diligence That Protects Family Capital
- Passing the Baton: Estate Planning and Succession for a Family Franchise
- Financial Literacy: Preparing the Next Generation to Keep What You Build
- Why Your Future Franchise
- Questions Families Ask About Franchising and Generational Wealth
What Generational Wealth Means for a Franchise Family
Generational wealth means assets passed down between generations rather than earnings spent within one lifetime. A salary ends when the job ends. An asset keeps working after you stop, and the families who hold it can sell it, transfer it, or borrow against it long after the first generation has retired.
Common examples of generational wealth include:
- A paid-off family home or rental property.
- Investments and retirement accounts left to the next generation.
- A family business with documented systems, a customer base, and resale value.
- Education paid for in full, which removes debt from the next generation’s starting line.
- Non-financial assets such as work ethic, financial knowledge, and relationships, which families pass on whether they plan to or not.
Notice that the list mixes financial assets with non-financial assets. Families that keep wealth across three generations tend to pass down both, and the second kind matters more than most first-generation owners expect.
Why is generational wealth important to the families we talk to? Because most of them started with none. They built a career from a standing start, and they know how much of that effort went into simply catching up. Wealth held across multiple generations changes what future generations can attempt: a house bought younger, a degree without loans, a business started with a safety net instead of a credit card. The importance of that head start becomes obvious to anyone who never had one.
The numbers explain the urgency. In the Federal Reserve’s 2022 Survey of Consumer Finances, the wealth of the typical Black family came to about 15% of the typical White family. The World Inequality Report 2022 found the richest 10% of the global population holding 76% of all wealth. Families outside those brackets rarely close the gap through wages alone. They close it by owning something, and then by preserving wealth long enough to hand it on.
Building generational wealth through business ownership sits at the center of this guide because it addresses both problems at once. The business helps create the initial wealth, and it gives future generations a place to learn the skills and knowledge that keep wealth in the family. Preserving wealth across three generations is no simple task, and families that treat it as one usually end up as the 90% statistic in the box below.
Questions We Get Asked
Why is generational wealth important if my kids will earn their own living? Because earning power and wealth diverge. Women earned an average of 85% of what men earned in 2024, according to Pew Research Center, a gap that compounds over a working life and affects how much a daughter can save on her own. Assets you pass down remove that ceiling for the people who inherit them.
What does “shirtsleeves to shirtsleeves in three generations” mean? The first generation builds the wealth, the second generation maintains it, and the third generation, raised without the struggle, spends it. The Williams Group study behind the 90% figure attributes most of that loss to a breakdown in trust and communication inside the family, not to taxes or bad investments.
Does a franchise count as generational wealth? It can, if it produces an income stream, holds resale value, and has a transfer path written into the agreement. A business that depends entirely on the founder’s presence rarely survives the founder’s exit, which explains why documented franchise systems appeal to families thinking past one generation.
Franchise Investment Opportunities Worth a Closer Look
Franchise investment opportunities involve purchasing the rights to operate a proven business model under an established brand, with training, marketing, and technology supplied by the franchisor. Which categories deserve a family’s attention right now depends on demand that will still exist when the next two generations take over. Not every category builds generational wealth equally. We do not recommend brands in an article, and we prescreen every franchisor we introduce, so what follows covers industries rather than names.
Home Services and Commercial and Residential Services
Most homeowners either cannot or will not fix their own roof, repair their own HVAC, or clean their own gutters, and that demand does not disappear in a downturn. The 2026 IFA Franchising Economic Outlook puts commercial and residential services among the fastest-growing franchise industries at 3.2% year over year, and Georgia sits among the top performing states for franchise growth. Scott describes the trades as booming, with strong margins and franchisor technology that makes booking and scheduling easy for the customer. For families, these businesses also create the clearest path for a teenager to start on a truck and learn the work from the ground up.
Senior Care and Preventive Healthcare
Preventive healthcare now stands as the third-largest franchised industry in the United States, according to the same IFA report. In-home senior care sits alongside it as an aging population needs more help at home. These businesses carry real compliance and staffing responsibilities, and they reward owners who lead people well. They suit families with a second generation drawn to healthcare or hospitality careers.
Fitness, Wellness, and Child Services
Fitness and wellness franchises benefit from a customer base that keeps investing in health, and child services tie with residential services for the fastest projected growth in 2026. Scott started his own franchise career at 22 in a personal training concept, then grew to three locations and later the area rights for New York City, so we know the model from the inside. Membership businesses produce recurring revenue that lenders and future buyers understand.
Business-to-Business Services
Commercial cleaning, staffing, payments, and consulting concepts sell to companies rather than consumers, often with contracts that renew year after year. Many run without a storefront and with a small team, an advantage for an owner who wants to build a business around existing corporate relationships. Our guide to B2B service franchise ownership covers the day-to-day reality of that model.
Operating Models: Owner-Operator, Semi-Passive, Solo, and Multi-Unit
Category matters less than the operating model when the goal spans three generations. Ask which of these fits the person who will actually run the business:
| Model | Recommended Approach | Key Difference |
|---|---|---|
| Owner-operator | Run the location yourself day to day. | Highest control, but also the highest time commitment. |
| Semi-passive | Hire a general manager to run daily operations while you oversee the manager, financials, vendors and landlord relationships. | Requires more capital and a strong hire. Can suit someone keeping a corporate role while the business ramps up. |
| Solo | Choose a concept where you can operate without a team, building your own customer pipeline and keeping overhead low. | Lower overhead and fewer staffing requirements, but you are investing more of your own time. |
| Multi-unit | Prove the first unit before expanding into additional territories. | Greater potential for enterprise value, but also greater financial and operational complexity. |
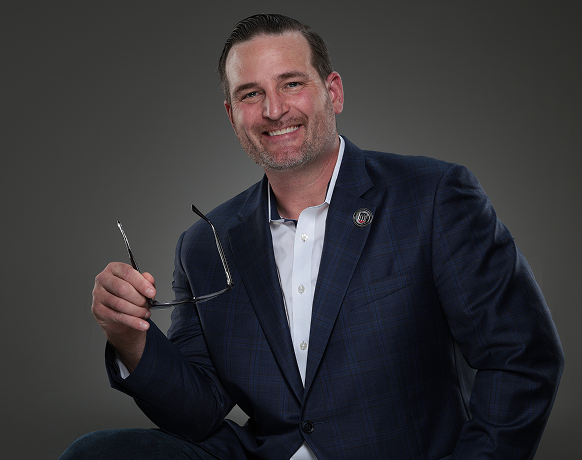
“Franchising is not a completely passive business. The dream is free, the hustle is work.”
Scott Thompson
Lead Franchise Consultant, Your Future Franchise
Connect on LinkedIn
Watch Out: Market fit and local demand affect the outcome of any franchise investment as much as the category does. A concept that thrives in one metro can struggle 40 miles away. Check the customer counts in Item 19 against the territory you plan to buy, and talk to franchisees in markets that resemble yours before you commit.
Wealth Building Strategies That Separate Ownership From a Salary
The wealth-building strategies available to a business owner differ from those available to an employee, and most first-time candidates have never seen them laid out. A W-2 earner receives pay after taxes, then covers living expenses from what remains. An owner can manage the cash flow of the business, decide how and when to take compensation, and build equity in an asset at the same time. That combination explains why so many wealth-building strategies for families start with business ownership or real estate rather than with a bigger paycheck.
Four levers matter most for a family thinking in generations:
- An income stream plus equity: The business pays you while you own it and, if built well, pays you again when you sell it or transfer it. Item 20 of the FDD shows how often units in the system change hands, which hints at whether a resale market exists.
- Pre-tax cash flow: Scott points out that certain legitimate expenses, such as a home office, vehicle use, or business meals, may run through the business rather than through post-tax pay. The rules depend on your situation and require a CPA’s guidance, not a blog’s.
- White space for the next owner: A buyer, whether a multi-unit operator, a private equity group, or your own child, pays for room to grow. Territory you can expand into later adds to enterprise value.
- Diversification across assets: A franchise sits alongside retirement accounts, real estate, and taxable investments in family wealth planning. It should not replace all of them, and investing every dollar the family has in one location leaves no margin for a slow first year.
Taxes touch every one of those levers. Owners pay taxes on business profit, on compensation, on a sale, and eventually on a transfer to heirs, and the entity structure chosen at the start affects all four. Tax efficiency deserves its own conversation with a tax professional. Scott notes that the U.S. tax code favors people who own businesses and property over people who only earn wages, and that most corporate professionals have spent an entire career on the wage side. Understanding that difference early shapes better investment decisions later, and a CPA who knows small businesses can show you what applies to your family.
For example, a family that plans to hold the business for 20 years and then transfer it to a child faces one set of tax planning questions. A family that intends to build three units and sell to a private equity buyer faces another. Neither plan beats the other. The point of financial planning at this stage lies in choosing one on purpose, so that every later decision, from the entity type to the second location, serves the same clear plan.
“I’m building an annuity for myself. That’s what it is. I’m parking cash and other vehicles to create a long-term annuity.”
Scott Thompson
Lead Franchise Consultant, Your Future Franchise
Connect on LinkedIn
Good to Know: Any claim a franchisor makes about sales, income, or profits must appear in Item 19 of the FDD. The FTC states that no other spoken or written financial performance claim may be made if it does not appear there. If a salesperson quotes numbers that live outside Item 19, treat that as a red flag rather than a bonus. As with all investments, no franchise carries a guarantee of success.
Financial Qualification: Liquid Capital, Net Worth, and Funding
Financial requirements vary widely by franchise. Many franchisors set minimum liquid capital and net worth requirements, and the total initial investment should be verified in Item 7 of each brand’s FDD. In our consulting practice, candidates with $100,000 to $200,000 in available liquid capital generally see a broader range of opportunities to evaluate. The right number for your family depends on the category, the model, and how many locations you intend to open. It also depends on how the purchase fits the rest of the family wealth picture.
Before any brand conversation, Scott asks candidates to build a family budget. Know what it costs to run your household for a year, taxes included, then compare it to a worst-case ramp in the business. Total capital requirements should include not only the initial franchise fee but also ongoing operating costs, payroll, marketing, and the living expenses the FTC suggests planning for up to two years.
Families funding a franchise usually draw on several resources, and the funding strategies that work combine more than one:
- Personal savings and taxable investments.
- Retirement accounts, through a properly structured Rollover as Business Start-Up (ROBS) arrangement to invest eligible retirement assets. These carry meaningful tax and compliance requirements and call for experienced retirement plan and tax professionals.
- Lending. Some lenders are familiar with financing established franchise systems, but approval, pricing, and terms still depend on the borrower, the brand, the loan structure, and the lender’s underwriting.
- Family capital, with the ownership stake and the repayment terms in writing before the first dollar moves.
Our article on franchise funding options covers each path in depth, and our franchise investment strategy guide explains how to match the capital you have to the model you want.
Watch Out: Item 7 only requires the franchisor to estimate about three months of additional funds. Scott sees more families choke a good business through undercapitalization than through any other mistake. When cash runs tight, owners pay themselves first, cut marketing, and starve the growth that would have carried the family through year two.
FDD Due Diligence That Protects Family Capital
The Franchise Disclosure Document contains the financial and operational information that separates a family decision from a family gamble. Evaluating a franchise investment requires careful analysis of the legal documents and financial disclosures, and no amount of enthusiasm from a franchisor’s sales team replaces that reading. Family wealth survives the deals you walk away from as much as the ones you close. We walk every candidate through it, and we still insist on a franchise attorney’s review before signing.
For a family building generational wealth, these items matter most:
- Items 5 through 7: The initial franchise fee, ongoing fees, and the estimated initial investment. Royalties, typically a percentage of gross sales, continue whether or not the business turns a profit.
- Item 11: Training and support the franchisor provides, which your successor will benefit from more than you will.
- Item 12: Territory protections, and whether your children could expand into adjacent territory later.
- Item 17: Renewal, termination, and transfer terms, including what the franchisor requires to approve a transfer to a family member.
- Item 19: Financial performance representations, which show what existing locations report and give you the baseline for a good, better, and best pro forma.
- Item 20: Contact details for current and former franchisees. The FTC calls talking to them possibly the most reliable way to verify a franchisor’s claims.
A well-conducted financial analysis covers cash flow, break-even timing, and a realistic range of outcomes rather than a single best case. Due diligence should include speaking with existing franchisees about their actual experience, their staffing challenges, and how long it took them to reach the numbers in Item 19. Our FDD guide and our breakdown of the FDD explained cover every item in plain language.
Checklist: Family Due Diligence Before You Sign
✓ Item 7 investment compared against your household budget and a 12-month worst-case.
✓ Item 17 transfer clause reviewed with a franchise attorney, with the family member succession path confirmed in writing.
✓ Validation calls completed with at least five franchisees, including two who left the system.
✓ Ownership entity, buy-sell terms, and estate plan updates discussed with a CPA and an estate attorney.
✓ Financial advisor consulted on how the purchase fits the rest of the family wealth plan.
Questions We Get Asked
What separates a strong franchise system from a weak one? Strong systems combine corporate support, comprehensive operational training, and technology that helps franchisees acquire and keep customers. Understanding the financial commitment, ongoing fees, franchisee support, and territory protections tells you more than the brand’s marketing ever will. Our guide to franchise system evaluation lists the questions to ask.
Why do validation calls matter so much? Franchisees have no sales quota. They will tell you how long the ramp took, what the franchisor got wrong, and whether they would buy again. Scott builds his entire risk mitigation approach on Item 19 plus honest conversations with owners already in the system.
Do I need an attorney if the franchisor’s contract looks standard? Yes. Franchise agreements favor the franchisor by design, and the transfer, renewal, and termination clauses decide whether your family keeps the business. Our article on franchise agreements explains where the traps sit.
Passing the Baton: Estate Planning and Succession for a Family Franchise
Building generational wealth through a franchise fails at the handoff more often than at the launch. The founder knows every vendor, every employee, and every number. The child inherits a signature line and a franchisor who has never met them. Strategic estate planning and a written succession plan close that gap, and the work starts years before anyone plans to retire.
Wealth transfer inside a family business involves three separate transfers, and families often plan for only one. Skip any of the three, and the other two lose most of their value for the generations that follow.
- Ownership moves through the estate plan.
- Leadership continues through training and a franchisor-approved transfer.
- Knowledge transfers through years of the successor working alongside the founder.
Estate Planning and Wealth Transfer for Business Interests
A comprehensive estate plan forms the backbone of any wealth transfer, and a franchise complicates it in ways a brokerage account does not. Business interests differ from liquid assets as they need a valuation, an ownership entity, and instructions for what happens if the owner dies, becomes disabled, or divorces before the agreement ends. Taxes and their timing run alongside estate planning, because the timing and structure of a transfer can change how much of the family wealth actually reaches the heirs. Wealth managers and an estate attorney who understand closely held businesses handle that work with you, and we introduce candidates to those financial professionals as part of our network.
The succession strategies we see done well include:
- Choosing the successor on skills and interest, not birth order. Not every child wants the business, and forcing it produces a reluctant owner and a declining asset.
- Defining roles for family members who work in the business, with job descriptions, pay tied to the role, and the same accountability applied to everyone else.
- Confirming the franchisor’s transfer requirements under Item 17 and the franchise agreement, including training the successor must complete and any transfer fee.
- Creating an ownership structure with an entity, a buy-sell agreement, and life insurance where appropriate, so a death or divorce does not force a sale.
- Coordinating tax planning and wealth transfer with financial professionals who understand business interests, then documenting the plan so every family member can find it.
- Reviewing the estate plan after every major life change, such as a birth, a marriage, a second location, or a sale. Estate planning done once and filed away rarely matches the family that exists 10 years later.
Family Dynamics and the Conversations Most Families Avoid
Family dynamics can undo a business faster than a recession. One child works in the business, and the other does not. A divorce puts a stake in the hands of a former spouse. Two siblings disagree on whether to sell. Divorces and disputes fragment family assets, and once a stake sits with someone who never wanted it, preserving wealth becomes a legal problem rather than something the family can manage.
Families that discuss values and expectations early reduce that chaos, and clear communication does more for preserving family wealth than any trust structure on its own. The families we see manage this well talk about the wealth transfer plan early and often, in plain terms, with everyone who has a stake in the outcome. They explain who gets what, why, and what the business needs from each of them. The families who avoid the conversation leave it to a lawyer’s letter after a funeral.
The data suggests most families skip these steps. Cerulli Associates reported in September 2025 that only 27% of investors expecting an inheritance plan to keep their parents’ financial advisor, and only 20% of those who have already inherited did so. Children who never met the advisor rarely trust the plan. Bring the next generation into the room while you still run the business, and give them access to the same financial resources and advisors you rely on.
Questions We Get Asked
When should a family start wealth planning around the franchise? Before signing. The entity that buys the franchise, the way the family funds it, and the names on the agreement all shape the eventual transfer, and changing them later costs money and sometimes requires franchisor consent. Wealth planning at the start costs a few professional hours. Wealth planning after a death costs far more.
How often should we revisit the estate plan? After every major life change and at least every few years regardless. A second location, a child joining the business, a marriage, or a change in tax law each justifies a review. Families that treat estate planning as a living document keep the plan aligned with the business as it grows.
Does the franchisor have any say in who inherits? Usually yes. Most agreements require the franchisor to approve any transferee, including a family member, and the successor typically completes the brand’s training. Read the transfer and death provisions with a franchise attorney so the estate plan and the franchise agreement say the same thing.
“I always try to get people’s personal, compelling reason why they want to do this. Not just I want to own a business. It’s I want to own a business because I want to change my family tree.”
Scott Thompson
Lead Franchise Consultant, Your Future Franchise
Connect on LinkedIn
💡 Pro Tip
Hold a family meeting once a year with the business financials on the table, even while the children remain in school. Explain what the royalty pays for, what the payroll costs, what the business pays in taxes, and what the business would sell for today. Heirs who can read the numbers protect the asset. Heirs who only see the lifestyle spend it.
Financial Literacy: Preparing the Next Generation to Keep What You Build
Financial literacy decides whether generational wealth survives the second handoff. A franchise can create something a brokerage account cannot: a place where younger generations can learn money management by doing the work, reading a profit and loss statement, and watching what a slow month does to cash. Financial education inside the business beats financial education from a textbook, because the consequences show up on Friday’s payroll.
The national picture shows why financial education matters. The FINRA Foundation’s 2025 National Financial Capability Study found that:
- Only 46% of U.S. adults have set aside enough to cover three months of living expenses, down from 53% in 2021.
- 80% of college graduates hold a retirement account compared with 37% of adults with no college experience.
Higher financial literacy tracks with better savings habits, less costly debt, and fewer risky investment decisions, and the study shows the gap between those who have it and those who do not widening rather than closing. Financial literacy matters most for first-time wealth creators, since they have no family playbook to fall back on and no one to catch a mistake.
Financial Education for Future Generations
Strategies for teaching financial literacy inside a family business can look like this:
- A first job on the schedule at 16, for example, paid at the same rate as any other employee.
- Access to the monthly numbers review by the early 20s, with one line of the P&L to own, manage, and explain.
- Participation in validation calls and FDD review when the family evaluates a second location.
- A defined path to a management role, earned on performance, before any ownership conversation begins.
- Exposure to the family’s financial professionals and other resources, so the successor already trusts the CPA and the estate attorney when the transfer arrives.
The habits pass down alongside the assets, and the skills transfer faster than the money. Scott describes the greatest franchisees as continuous learners who take ownership of mistakes, and children who watch a parent run a business that way absorb it. That non-financial inheritance, the work ethic and the judgment, outlasts any single location, and it travels from one generation to the next without a single tax form.
Education of this kind also protects generational wealth from the second generation trap. Heirs who understand how the wealth got created tend to respect it. Heirs who only saw the results tend to spend it, and no estate plan fixes that. The advantage of a franchise here comes from proximity, where the business sits close enough to daily life that younger generations learn by watching, then by doing, then by owning.
“They’ve sold the business, they’re retired now, and now all they do is refer their nieces to me, and one of their nieces bought a franchise from me. So I think kind of helping the generational wealth within their family continue to expand by helping people find the right fit for themselves.”
Scott Thompson
Lead Franchise Consultant, Your Future Franchise
Connect on LinkedIn
Good to Know: Homeownership remains the way most American families start building wealth, and a franchise can sit on top of that foundation rather than replace it. Some owners eventually buy the building their location occupies, which adds real estate to the family assets and a second income stream in rent, with its own taxes and upkeep. Discuss that structure with a CPA before you sign a lease, since the entity that owns the property should rarely be the entity that runs the business.
Why Your Future Franchise
Advice about building generational wealth through franchising carries more weight when it comes from someone who has bought, built, sold, and funded franchises with his own money. Scott Thompson spent more than 25 years as a franchisee, a franchisor executive, and a private equity operator before founding Your Future Franchise. He currently holds an investment in a franchise his own family operates in Athens, Georgia.
Candidates nationwide, and especially in the Atlanta, Georgia market, work with us for reasons tied to long-term planning:
- Direct experience on both sides of the franchise agreement, not a consultant who has never signed one.
- A faculty role at the University of Georgia, where Scott teaches what he practices.
- Prescreened franchisor connections through the FranChoice network, and a curated portfolio of 10 to 12 high-performing franchise brands rather than a list of hundreds.
- A focus on fit and matching rather than lead generation. We prescreen candidates and franchisors alike to prevent costly mismatches before anyone commits.
- A no-fee model for candidates. Franchisors compensate us when an introduced candidate purchases a franchise, so you never pay a consulting fee. Independent attorneys, accountants, and lenders charge for their own services.
- Access to an extensive network of adjacent professionals, including franchise attorneys, lenders, CPAs, and wealth managers, who support candidates through closing and into the wealth planning that follows.
- A view of franchising shaped by families, not transactions. Scott has watched placements sell their businesses, retire, and send the next generation back to us, which tells us more about the model than any brochure.
Our 7-step consulting process begins with a 20-minute introductory call and a confidential questionnaire, moves into a two-hour consultation that builds your business model, and only then introduces two to four prescreened brands. Candidates comparing paths often start with our piece on leaving corporate for franchising, and the stories on our reviews page show what the outcome looks like for real families.
Ready to Build Something Your Family Can Keep?
Schedule a no-pressure consultation with Your Future Franchise to talk through the business, the family, and the wealth you want it to create. Franchisors compensate us when an introduced candidate purchases a franchise, so there is no cost to you for the consulting process.
Questions Families Ask About Franchising and Generational Wealth
What are the best franchise categories for building generational wealth?
The best category for your family depends on who will run it and for how long. Service industries with recurring demand, such as home services, senior care, child services, and business-to-business concepts, tend to hold value across economic conditions and transfer more cleanly to a successor. Membership and contract models produce recurring revenue that a future buyer can underwrite. Match the category to your successor’s interests, then verify the unit economics in Item 19 and with existing franchisees.
How do I pass a franchise to my children?
Start with the franchise agreement. Item 17 of the FDD and the agreement itself explain whether transfers to family members require franchisor approval, what training the successor must complete, and whether a transfer fee applies. Then work with an estate attorney and a CPA to structure the ownership entity, a buy-sell agreement, and the taxes due on the transfer. Wealth transfer done well starts a decade early. Bring the child into the business early enough to earn the franchisor’s confidence before the handoff.
Can my kids work in the franchise while still in school?
In most concepts, yes, subject to state labor laws for minors and the franchisor’s own policies. Many families put teenagers on the schedule for entry roles, which teaches accountability and gives the child a realistic view of the work. Pay them the same rate as other employees and hold them to the same standard, or the rest of the team will notice.
What happens to the franchise if I die before the agreement ends?
The franchise agreement governs it, and the answer varies by brand. Some agreements allow an estate or heir a set period to qualify as the new franchisee or to sell the business. Life insurance, a named successor, and an ownership entity with clear terms prevent a forced sale at the worst possible time. Review the death and disability provisions with a franchise attorney before you sign.
Is a franchise better than real estate for generational wealth?
Neither one replaces the other. Real estate offers appreciation and rental income with lower daily involvement. A franchise offers an operating business with cash flow, equity, and a place to train the next generation, along with more work. Many owners end up with both, sometimes by buying the building their location occupies, and family wealth tends to benefit from the mix. Investing in both takes capital, so a financial advisor can help you weigh the two against your family’s timeline, other investments, and risk tolerance.
How much money do I need to start a franchise for my family?
Financial requirements vary widely by franchise, and the total initial investment for any brand appears in Item 7 of its FDD. The initial franchise fee alone commonly runs from tens of thousands to several hundred thousand dollars, per the FTC, with buildout, equipment, inventory, and working capital on top. In our consulting practice, candidates with $100,000 to $200,000 in available liquid capital generally see a broader range of opportunities to evaluate.
Do I have to pay Your Future Franchise for consulting?
No. Franchisors compensate us when an introduced candidate purchases a franchise, so candidates never pay a consulting fee. The independent attorneys, accountants, and lenders we introduce charge for their own services, and we recommend using them. Our role covers the fit, the prescreening, access to our professional network, and the guidance through the FDD and validation stages.
What if my children do not want the business?
Then the business becomes an asset to sell rather than an asset to transfer, and that outcome still builds family wealth. A well-run franchise with documented systems, a stable team, and room to grow attracts buyers inside the system and outside it, and the proceeds can fund the investments, education, or property that carry future generations forward instead. Plan for both paths from the start: build the business as if a stranger will one day buy it, and let your children decide with full information rather than obligation.
Where should a family begin?
With a conversation about what you want the business to do for the generations who come after you. Write down the lifestyle you want, the money the household needs, and the role each family member might play, then book a 20-minute call with us. From there, the confidential questionnaire and consultation turn those answers into a business model that filters franchise investment opportunities down to the few worth your family’s capital and time.